S Corporation Tax Planning for Business Owners
Learn what business owners should know about S Corp tax planning, including reasonable compensation, salary vs. distributions, and when to revisit...
7 min read
North Carolina franchise tax is generally a tax on the privilege of doing business in the state—not a tax on gross receipts or corporate income. For most corporations, the current calculation begins with adjusted year-end net worth, applies the appropriate North Carolina apportionment factor, and then applies the C corporation or S corporation rate.
North Carolina imposes an annual franchise or privilege tax on domestic and foreign corporations doing business in the state. The tax is separate from North Carolina corporate income tax, although both taxes are generally reported on the same corporate return. A corporation may owe franchise tax even when its activities are protected from North Carolina income tax under Public Law 86-272.
Corporations generally file Form CD-405, while S corporations generally file Form CD-401S. Domestic corporations and foreign corporations with a North Carolina certificate of authority—or that are otherwise doing business in North Carolina—may have a filing obligation even if they are inactive or have no net income.
The current tax base is net worth
For tax years beginning on or after January 1, 2023, North Carolina generally uses a net-worth-only franchise tax base. The former three-base system no longer applies to those years. Under the prior system, the tax base was generally the greatest of:
Those property-based alternatives were eliminated for current tax years.
North Carolina measures net worth as of the close of the corporation’s taxable year. The starting point is the corporation’s total assets, without initially reducing those assets for accumulated depreciation, depletion, or amortization, less total liabilities.
The statute then requires a deduction for accumulated depreciation, depletion, and amortization determined under the method used for federal tax purposes. In practical terms, the calculation generally resembles adjusted assets less liabilities, subject to North Carolina’s statutory adjustments. GAAP applies when the corporation maintains its books under GAAP. If it does not, the corporation generally uses the accounting method used for federal income tax purposes.
For a foreign entity filing a federal income tax return, North Carolina bases net worth on the value of assets deemed to be in the United States. This prevents foreign assets from being included in the franchise tax base when the applicable North Carolina rules measure only U.S. assets.
A corporation generally must add back indebtedness owed to a parent, subsidiary, affiliate, or certain non-corporate entities in which the corporation or affiliated group owns more than 50% of the capital interests. The adjustment applies unless the indebtedness creates qualified interest expense under North Carolina law.
The rule is intended to prevent related parties from reducing the franchise tax base through affiliated debt. A creditor corporation subject to North Carolina franchise tax may generally deduct the corresponding indebtedness to the extent the debtor corporation was required to add it.
A corporation should separately review related-party loans, inter-company payables, goods or supplies furnished by related entities, and other forms of capital advanced by affiliated parties. The treatment can depend on the identity of the creditor, ownership percentages, and whether the interest qualifies under the statutory exceptions.
An investment in a subsidiary generally does not reduce the net-worth base. However, special rules may apply when a corporation is required to include the assets of a non-corporate LLC in its franchise tax base. In that situation, the corporation may exclude its investment in the LLC to prevent the same value from being included twice.
North Carolina guidance also recognizes an exclusion for retained earnings of existing subsidiaries that the parent corporation has capitalized or recorded on its books through equity-method accounting. This is a separate issue from excluding a direct investment in an LLC and should be reviewed with the corporation’s balance sheet and accounting records.
A multi-state corporation does not necessarily pay franchise tax on all of its worldwide net worth. A corporation doing business in North Carolina and one or more other states generally apportions its net worth to North Carolina using the same fraction used to apportion its income under North Carolina corporate income tax rules. A corporation exempt from North Carolina income tax generally uses the factor it would have used if it were subject to income tax.
For a general business corporation, North Carolina generally uses a sales factor:
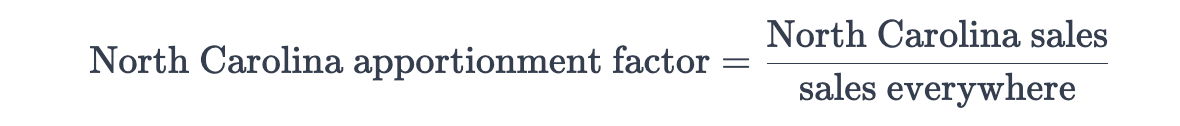
The factor is applied to the corporation’s adjusted net worth, not directly to gross receipts. For example:
The sales factor includes receipts from the corporation’s regular business operations, subject to exclusions for items such as casual sales of property, non-apportionable income, exempt receipts, returns of principal, and certain dividends. For services, receipts are generally sourced to North Carolina to the extent the service is delivered to a location in North Carolina. For tangible personal property, receipts are generally sourced to North Carolina when the property is received by the purchaser in the state.
A corporation that believes the statutory method overstates the amount of net worth attributable to North Carolina may request an alternative apportionment method. The corporation must submit a written request, explain why the statutory method is inappropriate, and demonstrate by clear, cogent, and convincing proof that the proposed method better reflects the corporation’s North Carolina business. The request generally must be made within 90 days after the regular or extended return due date, and the Department identifies a $5,000 fee for an alternative-apportionment written determination.
A non-corporate LLC is generally not itself subject to North Carolina franchise tax unless it elects to be taxed as a corporation for federal income tax purposes. However, a corporation that owns or constructively owns more than 50% of the capital interests in a non-corporate LLC may have to include the same percentage of the LLC’s assets in its own franchise tax base.
The principal rules are:
For an affiliated group, the attributed assets are allocated among the group members doing business in North Carolina. The allocation is based on each North Carolina group member’s capital interest compared with the capital interests owned by all group members doing business in the state.
For example, assume an affiliated group owns 100% of an LLC. Corporation A owns 51% and Corporation B owns 10%; the remaining 39% is owned by a group member that does not do business in North Carolina. Corporation A would generally include 83.61% of the LLC’s assets, calculated as 51% divided by the 61% owned by North Carolina group members. Corporation B would generally include 16.39%.
This rule applies to a non-corporate LLC. If an LLC is classified as a corporation for federal tax purposes, the LLC itself generally reports its North Carolina income and franchise tax obligations. A corporate member whose only North Carolina connection is its ownership interest generally does not file a separate corporate return, although additional North Carolina activities can change that result.
For tax years beginning on or after January 1, 2025, the franchise tax rates are:
| Entity | Rate structure |
|---|---|
| C corporation | $1.50 per $1,000 of tax base, with a maximum of $500 for the first $1,000,000 of tax base, plus $1.50 per $1,000 above $1,000,000 |
| S corporation | $200 for the first $1,000,000 of tax base, plus $1.50 per $1,000 above $1,000,000 |
| All corporations | Minimum tax of $200 |
The C corporation rate structure does not mean that the corporation pays $500 on its entire tax base. It caps the tax attributable to the first $1,000,000 at $500. The S corporation instead pays $200 for the first $1,000,000.
Using the $1,200,000 apportioned tax base above:
These amounts are before applicable credits and other return-level adjustments. They also illustrate why entity classification matters even when two corporations have the same adjusted net worth and apportionment factor.
A qualifying holding company has a separate maximum franchise tax of $150,000. A corporation generally qualifies as a holding company if it has no assets other than qualifying ownership interests or receives more than 80% of its gross income from corporations in which it owns more than 50% of the voting stock, voting capital interests, or ownership interests.
North Carolina corporate franchise and income tax returns are generally due on the 15th day of the fourth month after the close of the corporation’s income year. For tax years beginning on or after January 1, 2025, a corporation generally receives a seven-month filing extension. An automatic federal extension can create an automatic North Carolina extension if the corporation properly certifies the federal extension on its North Carolina return. Otherwise, Form CD-419 generally must be filed by the original due date.
An extension gives additional time to file, not additional time to pay. Franchise tax is due by the original statutory filing date. Late payment can result in interest and a 5% failure-to-pay penalty, while late filing can result in a 5% penalty for each month or part of a month, up to 25% of the additional tax due. A 20% collection assistance fee may also apply if a debt remains unpaid more than 60 days after a Notice of Collection, subject to the applicable payment or installment-agreement exception.
Common errors include:
Fraud involving intentional underpayment on assets attributable through a controlled LLC can constitute a Class H felony under North Carolina law. More broadly, North Carolina identifies additional civil and criminal penalties for fraud, negligence, frivolous returns, willful failure to file, and failure to provide information or pay tax.
The most important point about franchise tax NC is that the tax is generally based on adjusted, North Carolina-apportioned net worth—not gross receipts, taxable income, or North Carolina property alone. The correct calculation depends on year-end assets and liabilities, required affiliated-debt adjustments, the corporation’s apportionment factor, entity classification, and any controlled-LLC asset attribution.
Understanding the franchise tax NC calculation can help your business prepare for its filing and payment obligations. Stancil CPA can help review your accounting records, apportionment information, and entity structure before the return is filed. Schedule a consultation to discuss your North Carolina tax needs.
Learn what business owners should know about S Corp tax planning, including reasonable compensation, salary vs. distributions, and when to revisit...
Explore advanced tax planning strategies for high-income families in Raleigh, NC, including investments, charitable giving, and estate planning.
Quick Summary: Tax preparation reports what already happened—your historical income, expenses, and filings. Tax planning, by contrast, helps shape...